Photo: Daniel Brzdęk, via Unsplash.
August delivered a clear message to American households: prices are still rising faster than pay, and energy costs are increasing the pressure.
The Consumer Price Index rose 3.4% over the year in August, according to the Bureau of Labor Statistics. Average wage growth was tracked at approximately 3.1%, according to the reporting brief for this article. That creates an estimated 0.3 percentage-point gap between prices and pay.
The result is a decline in real purchasing power. A worker can receive a larger dollar paycheck and still afford less.
This article is an independent news analysis. Why Main Street is a member-owned financial education and social media platform. It is not a bank, broker, lender, tax adviser, or financial adviser. The information below is general education, not individualized financial advice. Readers remain responsible for verifying data and evaluating their own financial circumstances.
The August inflation report in four numbers
The August report contained four figures that matter to households, borrowers, savers, and investors:
- 3.4%: Annual headline CPI growth.
- 0.4%: Monthly CPI growth in August.
- 3.9%: Monthly increase in gasoline prices.
- 2.4%: Annual core CPI growth, excluding food and energy.
The headline annual rate was unchanged from July. The monthly increase, however, accelerated from July’s 0.1% gain.
Core CPI increased 0.3% during the month, according to CNBC’s report on the inflation data. That reading was higher than some forecasts and signaled that price pressure was not limited to gasoline.
Core inflation excludes food and energy because those categories can move sharply. That measure is useful, but it does not describe the full household experience. Consumers must still pay for fuel, electricity, transportation, and groceries.

Photo: Massimilianogalardi, CC BY-SA 3.0, via Wikimedia Commons.
Why gasoline is driving the squeeze
Gasoline prices rose 3.9% in August, accounting for more than one-third of the monthly CPI increase, according to the BLS release and CNBC’s inflation breakdown.
The broader energy index increased 2.1% during the month. On an annual basis, the energy category was up sharply, with gasoline prices more than 27% above their level a year earlier in the reported data.
Fuel costs affect more than drivers. Gasoline and diesel are inputs into transportation, delivery, agriculture, construction, and logistics. If fuel remains expensive, businesses can pass some of those costs through to customers.
That transmission process can reach grocery shelves, airline tickets, household goods, and services. The impact is not uniform, but the risk is straightforward: a temporary fuel shock can become a wider cost problem if it persists.
The Federal Reserve’s official calendar lists the next Federal Open Market Committee meeting for September 15–16, 2026. The August CPI report is among the final major inflation readings available before that meeting.
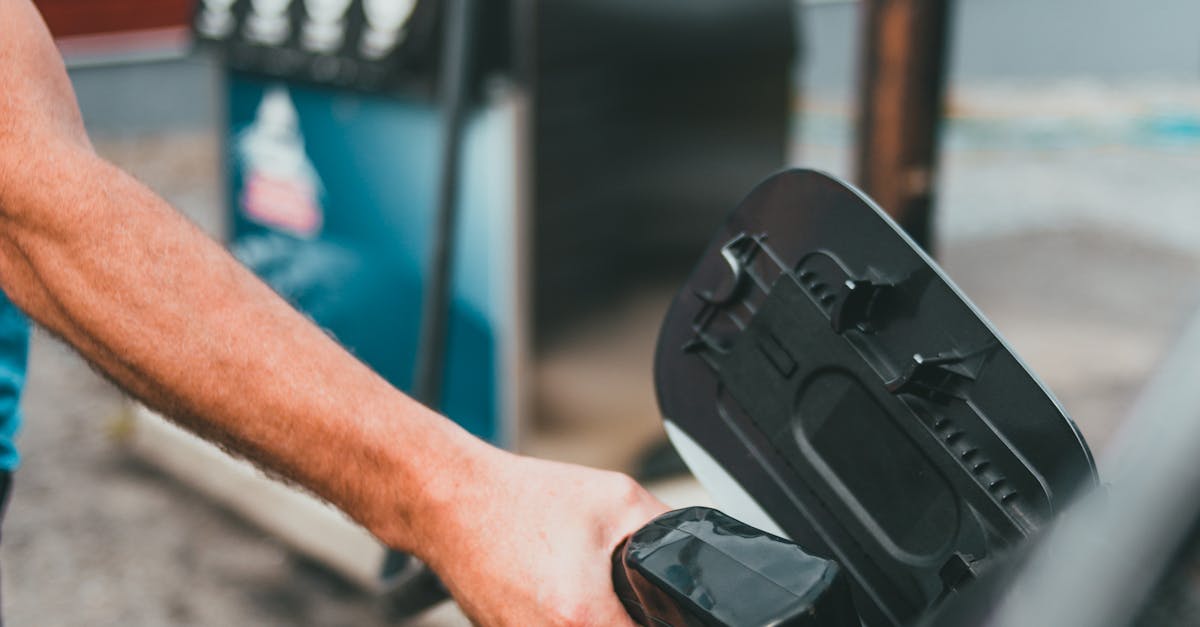
Photo: Erik McLean, via Pexels.
What the wage gap means for your paycheck
A 3.1% wage increase sounds positive in isolation. It is not enough to preserve purchasing power when consumer prices are rising at 3.4%.
The basic calculation is:
> Nominal wage growth − inflation = approximate real wage growth
Using the figures in the reporting brief:
> 3.1% − 3.4% = −0.3%
That does not mean every worker lost 0.3% of purchasing power. Wage growth varies by industry, occupation, seniority, geography, and employer. Household inflation also differs from the national CPI because spending habits differ.
A commuter with a long drive may experience more pressure than a remote worker. A renter facing a lease renewal may experience a different inflation rate than a homeowner with a fixed mortgage. A household with medical or child-care expenses may face costs that move differently from the headline index.
The point is narrower and more measurable: the average price level rose faster than the reported average wage measure. That is a negative development for purchasing power.
For workers, the practical effect can appear as:
- Less money remaining after groceries and fuel.
- Slower progress toward emergency savings.
- Greater reliance on credit cards or buy-now-pay-later products.
- Delayed retirement contributions or debt payments.
- Reduced flexibility when an unexpected bill arrives.
A paycheck calculator can make the difference visible. Compare last year’s take-home pay with current recurring expenses rather than looking only at the gross salary.

Photo: Anton Ehrola, CC BY-SA 4.0, via Wikimedia Commons.
What higher rates could mean for households
Market participants increased the probability of a quarter-point Federal Reserve rate increase after the August CPI report. CNBC reported that the implied odds moved to nearly 90%, based on the CME Group’s FedWatch tracker.
That probability is not a binding promise. It is a market estimate derived from futures pricing. The FOMC makes the statutory policy decision.
A 25-basis-point increase would affect different groups in different ways.
Borrowers
Credit-card interest rates generally respond quickly to changes in benchmark rates. Variable-rate loans may also become more expensive.
Mortgage rates do not move one-for-one with the federal funds rate, but Treasury yields, inflation expectations, and market volatility influence mortgage pricing. Borrowers considering a refinance should compare the projected monthly savings with closing costs and the expected time in the loan.
The relevant question is not simply whether rates might fall later. It is whether refinancing today produces a credible break-even period and improves the household’s financial position.
Savers
Higher rates can benefit savers, but only if their money is held in an account that adjusts.
Consumers should compare annual percentage yields on high-yield savings accounts, certificates of deposit, and money-market products. A large balance sitting in a low-yield checking account may lose purchasing power faster than necessary.
Rate shopping is not a guarantee against inflation. It is a way to reduce the opportunity cost of holding cash.
Investors
Higher rates can place pressure on interest-rate-sensitive assets, including some growth stocks, real estate investments, and long-duration bonds. They can also improve the income available from cash equivalents and short-term government securities.
Investors should avoid treating a single CPI report as a trading signal. A diversified plan, a defined time horizon, and appropriate risk controls matter more than a one-day market reaction.
Why Main Street does not manage portfolios or recommend securities. Readers should consult a qualified professional before making investment decisions.
Practical moves for an inflationary month
The August report does not require panic. It does require attention to cash flow.
1. Rebuild the household budget around current prices
Review the last 60 to 90 days of spending. Separate fixed obligations from flexible costs. Create a specific line for gasoline, utilities, groceries, and transportation.
Why Main Street previously covered a grocery strategy in “The 3-in-1 Grocery Shopping Method”. The method is not a universal solution, but systematic planning can reduce the effect of impulse purchases and price increases.
2. Compare savings rates
Check the current APY on savings and cash accounts. Review minimum balances, transfer rules, withdrawal limits, and whether the rate is promotional.
Do not move emergency funds into an account whose terms you do not understand. Liquidity and federal deposit insurance matter.
3. Set an energy-cost reserve
Gasoline and utility expenses can be volatile. A small monthly reserve can prevent an energy spike from becoming credit-card debt.
Drivers can also compare local fuel prices, combine errands, maintain tire pressure, and review whether commuting costs have changed materially.
4. Review refinancing timing
Borrowers should calculate the full cost of refinancing, not just the advertised rate. Include origination charges, appraisal costs, title expenses, points, and the potential effect of extending the loan term.
5. Protect long-term contributions where possible
A negative real-wage environment can tempt households to suspend retirement contributions entirely. That may be necessary for some families, but the decision should be deliberate.
Before reducing long-term savings, review subscriptions, discretionary purchases, insurance premiums, debt rates, and recurring fees. Small recurring cuts may preserve part of the contribution without creating a larger future gap.
The bottom line
August inflation was not a legal finding or a final verdict on the economy. It was a measurable warning.
Prices rose 3.4% over the year. Gasoline rose 3.9% in one month. Core inflation increased 0.3% monthly. If wages grew at approximately 3.1%, purchasing power declined modestly.
The Federal Reserve now faces a difficult statutory mandate: restrain inflation without causing unnecessary damage to employment and economic activity. Markets are pricing a high probability of a quarter-point hike at the September 15–16 meeting, but the decision remains pending.
Households do not control the CPI or the FOMC. They can control the quality of their cash-flow data, the rate paid on savings, the timing of major borrowing decisions, and the size of their energy reserve.
That is the immediate response to an inflation gap: measure the pressure, identify the avoidable costs, and protect the financial decisions that compound over time.
Sources: Bureau of Labor Statistics CPI release; CNBC inflation report; CNBC category breakdown; Federal Reserve FOMC calendar; AAA Gas Prices.
This article is for general informational purposes only. Why Main Street is not a bank, financial planner, investment adviser, tax professional, or lender, and does not guarantee the accuracy, completeness, or timeliness of third-party information. No statement in this article constitutes a recommendation to buy, sell, refinance, invest, or open any financial product.


Leave a Reply