The highest advertised APY is not always the highest return.
Some savings accounts cap the top rate at $5,000. Others require recurring deposits, direct deposit, debit-card activity, or credit-union membership. Promotional rates may expire. A technically superior APY can produce less interest than a lower flat rate if the account’s balance rules are unfavorable.
This ranking evaluates who actually qualifies for the advertised rate. Rates and terms reflect late-September 2026 snapshots and can change without notice.
> Disclosure: Why Main Street is not a bank, credit union, or financial institution. We do not provide financial advice and are not responsible for the accuracy or continued availability of third-party rates, terms, or products. Why Main Street may earn affiliate commissions from some links. Verify all information directly with the institution before opening or funding an account.
Why high-yield savings accounts matter in 2026
The FDIC reported a national average savings rate of 0.38% in August 2026. By comparison, high-yield savings accounts averaged approximately 3.65%, with leading advertised rates reaching 4.50%, according to rate comparisons from sources including Bankrate, The Wall Street Journal, Forbes Advisor, and NerdWallet.
That gap is material. On $10,000, earning 4.50% instead of 0.38% produces approximately $412 more interest over one year, assuming the rates remain unchanged and the balance stays constant.
The Federal Reserve’s September 16, 2026, rate decision also left short-term deposit rates elevated relative to recent years. That makes this a reasonable time to examine whether idle cash is earning a competitive return.
The FDIC’s August 2026 National Rates and Rate Caps data provides the baseline. The product terms below determine whether an individual can actually capture the advertised rate.
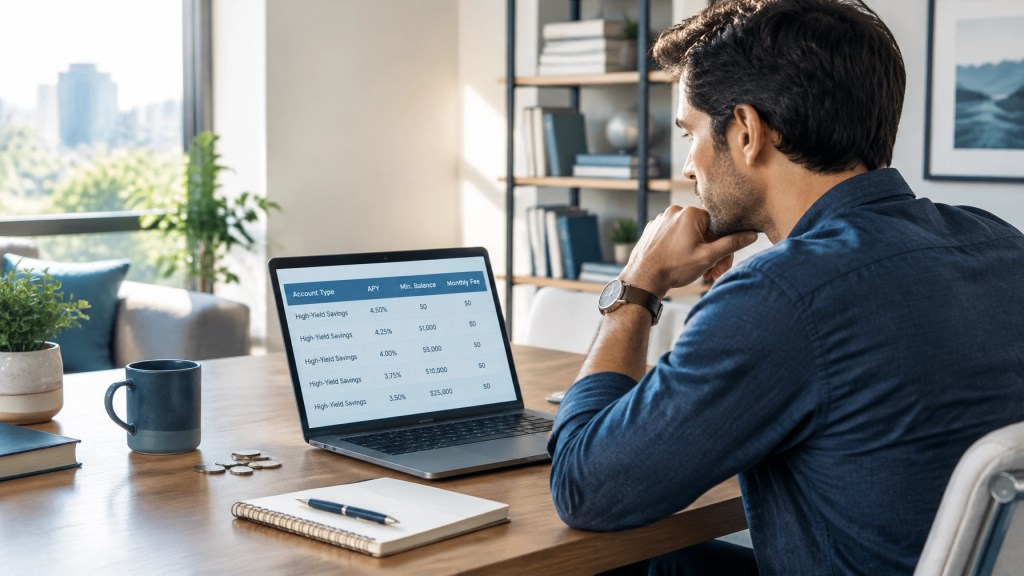
Comparison: APY versus qualification requirements
The table is a comparison tool, not an offer. Rates are variable unless expressly stated otherwise.
1. Best for a small balance: GO2bank or Elevault
For balances under $5,000, GO2bank offers the strongest headline rate in this group: 4.50% APY. The qualification is straightforward but restrictive. You need an active GO2bank checking account in good standing, and the 4.50% APY applies only to a combined savings-vault balance of up to $5,000. GO2bank states that balances above the cap do not earn interest. See the official GO2bank savings-vault terms.
Elevault is the cleaner alternative for someone who does not want a balance cap or recurring activity requirement. Its reported 4.34% APY requires no minimum deposit, and interest is calculated and paid daily. Elevault’s disclosures state that interest is paid on balances up to $500,000. Confirm the current partner-bank and insurance disclosures before transferring funds.
For a small-balance saver, the decision is therefore practical:
- Choose GO2bank if you already use its checking account and will keep no more than $5,000 in the vault.
- Choose Elevault if you want a higher flat-rate structure without a monthly deposit requirement.
- Choose Pibank if simplicity and a no-minimum structure matter more than the last fraction of a percentage point.
2. Best for a large balance: Elevault
Large balances expose the weakness of capped accounts.
St. Mary’s Credit Union advertises 4.50% APY on balances up to $50,000. That is competitive for the eligible member who satisfies its Kasasa requirements. However, the rate on funds above the top tier is substantially lower. GO2bank is even more restrictive because balances above $5,000 do not earn interest in the vault.
Elevault’s 4.34% APY, with interest paid on balances up to $500,000 according to its published disclosures, is better suited to a large cash reserve. Pibank at 4.10% and Vio Bank at 4.01% also use simpler structures than capped or activity-based accounts.
CIT can be competitive for balances of $5,000 or more, but its top APY depends on the current Boost terms. The account requires $100 to open, while the higher balance tier generally begins at $5,000. A promotion should not be treated as a permanent base rate.
Worked example: why the cap matters
Assume you deposit $20,000 for one year.
Cap-limited account at 4.50%:
- First $5,000 × 4.50% = $225
- Remaining $15,000 × 0% = $0
- Total interest = $225
- Effective yield on the full $20,000 = 1.125%
Flat-rate account at 4.10%:
- $20,000 × 4.10% = $820
- Effective yield = 4.10%
The account with the higher advertised APY produces $595 less interest in this example. The comparison is not theoretical. Balance caps can determine the actual return.

3. Best for recurring deposits: Happen Bank LevelUp Savings
Happen Bank’s LevelUp Savings account pays 4.20% APY when the account receives at least $250 in deposits during each evaluation period. The LevelUp rate applies to the full balance when the requirement is met. If the requirement is missed, the account falls to a lower standard rate.
This structure may suit employees who can route part of a paycheck into savings or savers who can automate a $250 monthly transfer. It is less suitable for someone who wants to deposit a lump sum and ignore the account.
The key question is not whether you can make the first $250 deposit. It is whether you can satisfy the requirement every month after the account’s introductory period. Review the official Happen LevelUp Savings terms before applying.
St. Mary’s Kasasa Saver is another activity-based option. It requires credit-union membership, a linked Kasasa checking account, at least one qualifying direct deposit or ACH transaction, 12 debit-card purchases, and eStatements during the monthly cycle to earn the rewards structure. That may be valuable for an active member. It is not pure simplicity.
4. Best for pure simplicity: Pibank Savings
Pibank’s reported 4.10% APY is designed around fewer conditions. Its disclosures state that there is no minimum balance to open or maintain the account, no monthly fee for the savings product, and no recurring deposit requirement for the stated APY.
Vio Bank offers a similar structure at 4.01% APY, with a $100 minimum opening deposit. Vio’s electronic-statement option generally avoids the monthly paper-statement fee. Both accounts require the same basic caution: the APY is variable and can change.
Recent account comparisons also show that the assumption that every high-yield account requires substantial starting capital is often incorrect. Approximately 76% of verified HYSAs can be opened with no minimum deposit, while about 90% charge no monthly maintenance fee, according to comparison data summarized by Financeradar and other deposit-account databases.

What to check before opening an account
Use this checklist before moving money:
- Base rate versus promotional rate: Determine when a boost expires and what rate applies afterward.
- Balance tiers: Confirm whether the APY applies to the entire balance or only a limited portion.
- Activity requirements: Check for direct deposit, monthly transfers, debit-card purchases, or linked checking requirements.
- Insurance status: Confirm FDIC coverage for a bank or NCUA coverage for a federally insured credit union.
- Transfer times: Review ACH deposit and withdrawal timelines before using the account for emergency funds.
- Withdrawal limits: Check transaction restrictions, transfer limits, and any excessive-withdrawal policies.
- Rate-change history: Because savings rates are generally variable, review how frequently the institution has changed the rate.
- Partner-bank structure: For fintech products, identify the actual insured bank holding the funds.
The standard FDIC insurance limit is $250,000 per depositor, per FDIC-insured institution, per ownership category. The same general limit applies through the NCUA Share Insurance Fund at federally insured credit unions. Read the FDIC deposit-insurance guidance and NCUA share-insurance guidance.
If you have more than $250,000 in cash, spreading funds across separately insured institutions or qualifying ownership categories can reduce uninsured exposure. Account titling matters. Use the FDIC’s Electronic Deposit Insurance Estimator for complicated structures.

Bottom line
The best high-yield savings account is determined by the rate you can actually earn.
- Under $5,000: GO2bank has the highest headline APY, while Elevault offers a less restrictive structure.
- Above $50,000: Elevault is more practical than accounts with sharp caps or lower overage tiers, subject to its current terms and insurance disclosures.
- With recurring deposits: Happen Bank can reward consistent monthly funding.
- For simplicity: Pibank and Vio Bank avoid many common qualification hurdles.
- For credit-union members: St. Mary’s can be competitive up to $50,000 if the monthly requirements are realistic.
Before opening an account, compare the effective return, not merely the number in the advertisement. For more financial education, budgeting discussions, and wealth-building resources, visit Why Main Street, an independent member-owned platform.
Rates change weekly. Verify every APY, balance tier, fee, insurance designation, and qualification rule directly with the institution before applying.


Leave a Reply